Mortgage Calculator

Use our Mortgage Calculator to estimate monthly payments, interest, taxes, insurance, and loan costs, then understand your mortgage with clear examples and an amortization schedule
Total Monthly Payment
$2,489.29
P&I

$2,022.62

Tax

$366.67

Insurance

$100

Total Interest

$408,143.2

Recent
Nothing here yetYour recent activity will appear here

What Is a Mortgage?

A mortgage is a loan used to buy a home. You repay it over time through monthly payments. Each payment may cover principal, interest, property taxes, homeowners insurance, PMI, and HOA fees, depending on the loan and property. Costs affect loan cost.
Mortgage Calculator for estimating monthly mortgage payments, interest, home loan costs, and total repayment.

How can you use our Mortgage Calculator?

Our Mortgage Calculator quickly calculates monthly mortgage payments and costs. Enter your home and loan details, then review the estimated payment and total interest.

Step 1

Enter Your Home Details

Enter the home price, down payment, and interest rate.

Step 2

Add Loan Costs

Enter the term, property tax, and insurance details.

Step 3

View Your Results

Get your monthly payment, tax, insurance, and interest instantly.

Step 4

Copy Your Result

Copy the calculated mortgage details for future use.

How to calculate mortgage payments manually?

A mortgage payment formula uses the loan amount, monthly interest rate, and number of payments. Formula: M=P[r(1+r)n]/[(1+r)n−1]M = P[r(1+r)^n] / [(1+r)^n - 1].

Formula

MM = monthly principal and interest payment.
PP = loan principal.
rr = monthly interest rate.
nn = total number of monthly payments.

Step by step guide

  1. Subtract the down payment from the home price to find the loan amount.
  2. Divide the annual interest rate by 12.
  3. Multiply the loan term by 12 to find total payments.
  4. Apply the formula to find monthly principal and interest.

Practical Example

For a 300,000homewith20300,000 home with 20% down, the loan is 240,000. At 6% for 30 years, the payment is about $1,439 per month.

What Does a Mortgage Payment Include?

A mortgage payment can include principal, interest, property taxes, homeowners insurance, PMI, and HOA fees.

Principal

Principal is the amount you borrow. Each payment reduces your loan balance, so less principal remains after every payment.

Interest

Interest is the lender's charge for lending money. Your early payments usually include more interest than principal.

Property Taxes

Property taxes fund local services. Your lender may collect part of each tax bill with your monthly mortgage payment.

Homeowners Insurance

Homeowners insurance helps protect the property from covered losses. Your lender may collect the premium through escrow.

PMI

PMI protects the lender when your down payment is small. It can raise your monthly payment until you meet removal rules.

HOA Fees

HOA fees pay for shared services and community upkeep. They usually sit outside principal and interest but affect housing costs.

Amortization schedule

An amortization schedule shows how each mortgage payment changes your principal, interest, and remaining loan balance over time. It helps you see the repayment path.

Year

Starting Balance

Annual Payment

Principal Paid

Interest Paid

Ending Balance

1

$240,000.00

$17,267.06

$2,947.23

$14,319.83

$237,052.77

2

$237,052.77

$17,267.06

$3,129.01

$14,138.05

$233,923.77

3

$233,923.77

$17,267.06

$3,322.00

$13,945.06

$230,601.77

4

$230,601.77

$17,267.06

$3,526.89

$13,740.16

$227,074.88

5

$227,074.88

$17,267.06

$3,744.42

$13,522.63

$223,330.46

Note: This sample schedule uses a $240,000 loan at 6% for 30 years. It excludes taxes, insurance, and HOA fees, so your full housing payment may differ.

History of Mortgages in the U.S.

U.S. mortgages changed as home lending grew. The Federal Housing Administration began in 1934 and helped expand long term home loans. Fannie Mae followed in 1938, while Freddie Mac began in 1970. Today, fixed rate and adjustable rate mortgages give buyers several ways to finance a home. Modern rules also guide lending, disclosures, and borrower protection.

Mortgage Calculator Components

These Mortgage Calculator components shape your payment. Enter each value carefully to get a clearer estimate of your monthly loan cost.

Loan amount

The loan amount shows how much you borrow after your down payment. A larger balance usually means a higher monthly payment.

Down payment

The down payment is the cash you pay upfront. A larger amount can reduce your loan balance and may reduce PMI costs.

Loan term

The loan term tells you how long you repay the mortgage. Longer terms can lower monthly payments but increase total interest.

Interest rate

The interest rate affects the cost of borrowing. A higher rate usually raises both your monthly payment and total interest.

Costs Associated with Home Ownership and Mortgages

Homeownership costs include regular mortgage expenses and one time buying costs. Add them to your estimate so the monthly and total cost feels realistic.

Recurring Costs

Recurring homeownership costs repeat monthly or yearly. They can raise your total housing cost beyond principal and interest. These costs can change over time.

Property taxes

Property taxes fund local services such as schools, roads, and public safety. Your tax amount depends on property value and local tax rules. Check your local rate.

Home insurance

Home insurance helps cover certain property losses and damage. Premiums depend on the home, location, coverage, and insurer. Include this cost in your estimate.

Private mortgage insurance (PMI)

Private mortgage insurance can apply with a smaller down payment. It adds to your monthly cost and protects the lender. Ask when PMI may end. Rules vary by loan.

HOA fee

An HOA fee covers shared services and community upkeep. Fees vary by property and may cover landscaping, amenities, or maintenance. Check current dues. Fees can rise over time.

Other costs

Other recurring costs can include utilities, repairs, maintenance, and routine services. These costs may not appear in a basic mortgage payment. Add them to your budget.

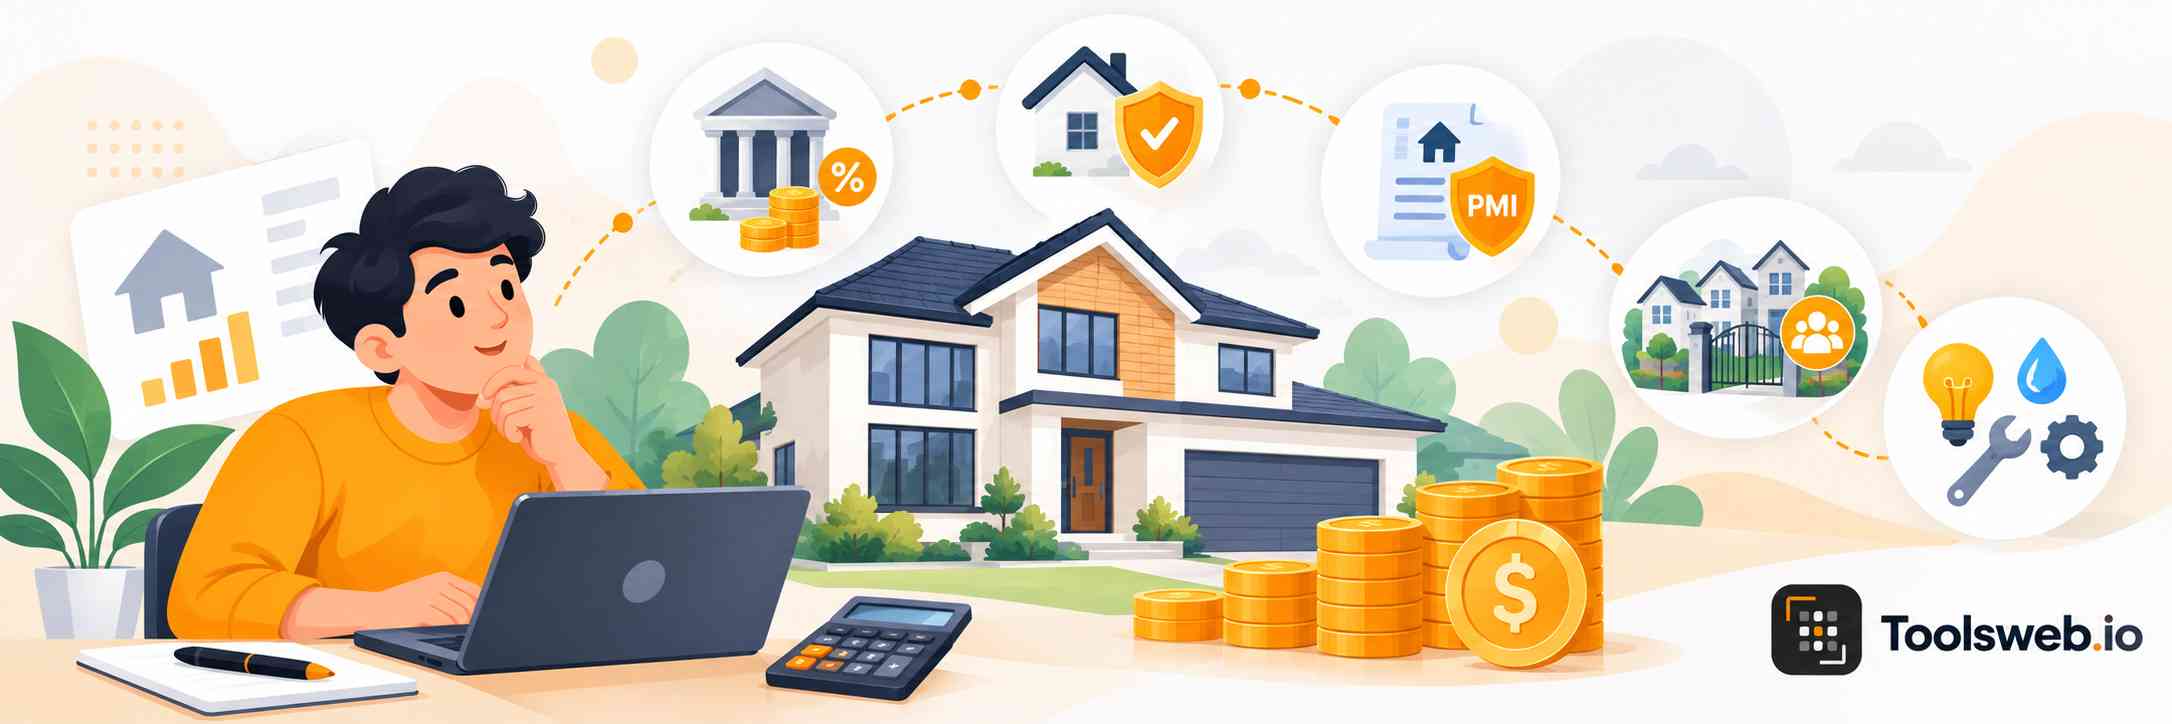
Recurring Costs illustration showing a homeowner reviewing ongoing housing expenses, mortgage payments, insurance, utilities, and other regular costs.

Non-Recurring Costs

Non recurring costs usually happen when you buy, sell, refinance, or improve a home. Plan for them separately from regular monthly payments because they affect upfront cash needs.

Closing costs

Closing costs can include lender fees, title services, appraisal charges, taxes, and other settlement costs. The amount varies by loan and location. Ask for an estimate.

Initial renovations

Initial renovations can include painting, flooring, repairs, appliances, or other upgrades. Set a clear budget before buying. Keep a reserve for unexpected work.

Miscellaneous

Miscellaneous costs may include moving, inspections, legal services, recording fees, or furnishings. Keep extra cash available for unexpected expenses not shown by the calculator.

Early Repayment and Extra Payments

Early mortgage repayment can reduce interest and shorten your loan. Compare the savings with penalties, lost cash flexibility, and other investment choices.

Early Repayment Strategies

You can repay a mortgage faster in several ways. Each strategy can reduce interest, but the savings depend on your loan terms and payment plan. Always check the lender's rules first.

Early Repayment Strategies for reducing mortgage interest, shortening the loan term, and paying off a home loan sooner.

Make extra payments

Make extra payments toward principal when your budget allows. Even small extra amounts can reduce interest and shorten the repayment period. This can also build equity faster.

Biweekly payments

Biweekly payments can create an extra monthly payment each year. Check how your lender applies partial payments before using this method. Confirm the lender accepts this payment setup.

Refinance to a loan with a shorter term

Refinancing to a shorter loan term can speed repayment. Compare the new rate, closing costs, and monthly payment before changing loans. The new payment may be higher.

Reasons for early repayment

Early repayment can lower borrowing costs and reduce the years you carry the mortgage. It may also provide a stronger sense of financial progress. Your goals should guide the choice.

Lower interest costs

Paying principal sooner leaves less balance for future interest charges. This can reduce the total interest you pay. Savings depend on your rate and balance.

Shorter repayment period

Extra principal payments can shorten the repayment period. You may own the home free and clear sooner, depending on the amount you pay. Compare the new monthly payment first.

Personal satisfaction

Some homeowners prefer owning their home sooner. Removing a mortgage payment can simplify future budgets and reduce financial obligations. It can also reduce monthly obligations later.

Reasons for early repayment of a mortgage, showing reduced interest, shorter loan terms, and lower repayment costs.

Drawbacks of early repayment

Early repayment has tradeoffs. Review your loan terms and personal finances before sending large extra payments toward the mortgage. Keep enough cash for emergencies before paying extra.

Possible prepayment penalties

Some loans may charge a prepayment penalty under specific terms. Check your loan documents or ask the lender before making large extra payments. Penalties vary by lender and loan.

Opportunity costs

Money used for early repayment cannot support other goals at the same time. Compare mortgage savings with savings, investments, or other debt payments.

Capital locked up in the house

Extra payments build home equity, but that cash stays tied to the property. Accessing it later may require a loan or home sale. That process can add costs.

Loss of tax deduction

Mortgage interest may affect your taxes in some situations, but rules depend on your circumstances. Do not assume early repayment always creates a tax loss.

Type of home loans to consider

Compare home loan types before choosing a mortgage. Each option has different rules for down payments, credit, rates, fees, and borrower eligibility.

Conventional loan (conforming loan)

A conventional loan comes from a private lender and follows standard rules. A conforming loan also meets limits for purchase by Fannie Mae or Freddie Mac.

FHA loan (government loan)

An FHA loan is insured by the Federal Housing Administration. It can support buyers with smaller down payments, but mortgage insurance rules apply.

VA loan (government loan)

A VA loan supports eligible veterans, service members, and some surviving spouses. It can offer flexible terms, but eligibility and lender rules apply.

USDA loan (government loan)

A USDA loan can help eligible buyers purchase homes in qualifying rural areas. Income, property, and borrower rules determine eligibility.

Jumbo mortgages (non-conforming)

A jumbo mortgage exceeds conforming loan limits. Lenders often apply stricter credit, income, reserve, and down payment requirements to these larger loans.

Explore Financial Calculators

Use financial calculators for loans, interest, investments, savings, taxes, and financial planning.

Frequently Asked Questions

These mortgage FAQs answer common questions about rates, affordability, appraisals, payments, loan terms, and the mortgage process.